

In the concentrated US equity market of 2024–25, owning the obvious winners was a remarkably profitable strategy. It also made a number of investment processes look clever.
One of the more intriguing examples came from Steven Edwards, who created 100 GPT-4o investor personas. They included value investors, growth investors, momentum traders, contrarians, quants and ESG specialists. Each selected 50 US-listed equities. Edwards aggregated their choices into a consensus portfolio and tested it over 561 trading days beginning in January 2024.
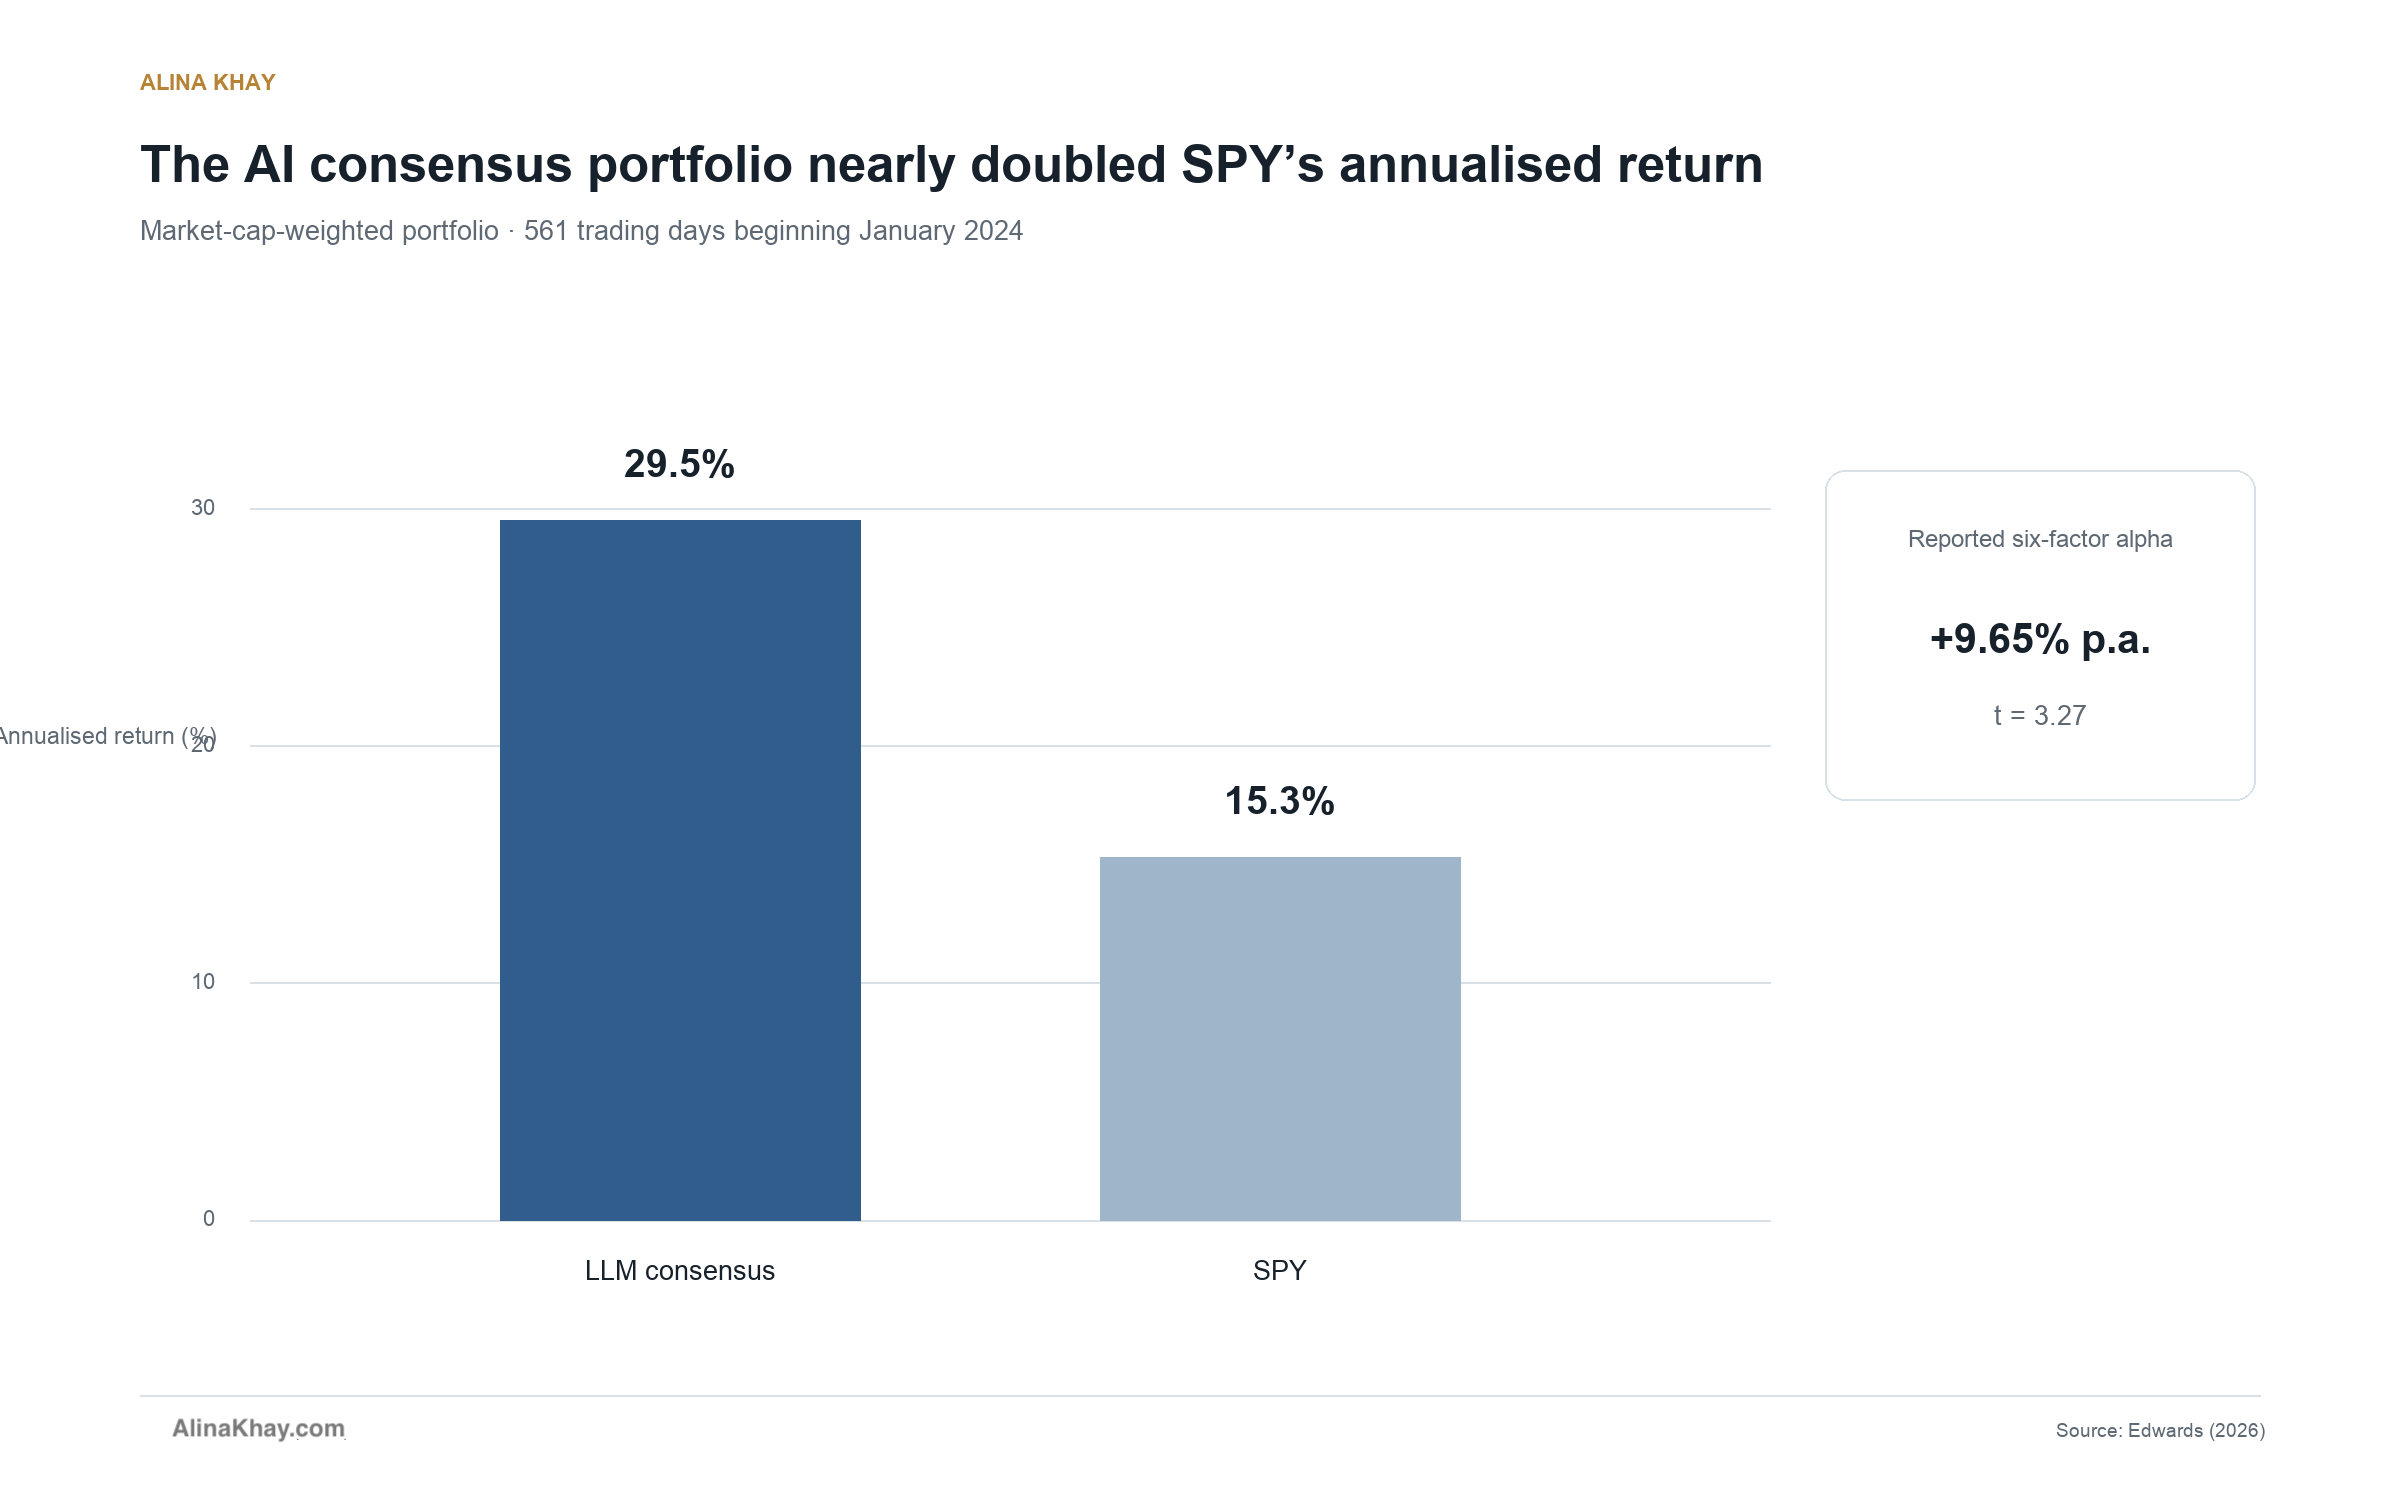
The market-capitalisation-weighted version returned 29.5% annualised, against 15.3% for the SPDR S&P 500 ETF. Even after controlling for six familiar market factors, the paper estimated annualised alpha of roughly 9.65%, with a t-statistic of 3.27. On the surface, the artificial committee had earned its fees.
Yet the most important result was not the return. It was what happened when 99 of the investors were dismissed.